Top 10 Companies That Buy Houses for Cash in Boise, ID
Selling a jointly owned Boise home during divorce gets difficult when the spouses disagree about timing, price, repairs, or who should remain in the property. One spouse may want a quick cash closing to stop carrying two housing costs, while the other may believe an MLS listing will protect more equity. Neither concern is automatically right or wrong.
The buyer is only one part of the decision. Before requesting offers, document each spouse's goals, ownership, mortgage obligations, estimated value, known liens, property condition, and any requirements from attorneys or the court. A useful overview of ownership issues appears in this guide to selling the house during a divorce.
The main paths are an MLS sale, a cash investor sale, a buyout, or a short sale if the debt and verified value leave insufficient proceeds. This roundup compares 10 cash-buying options in Boise, then explains how to compare them against the alternatives without letting speed obscure the financial or legal details.
Use this quick screen before contacting buyers:
- Urgency: Is foreclosure, relocation, probate, or a court deadline driving the sale?
- Condition: Can both spouses fund repairs, cleaning, staging, and showings?
- Equity: What remains after payoff statements, liens, taxes, closing costs, and approved expenses?
- Cooperation: Can both spouses communicate and sign consistently?
- Closing date: Does the household need a specific possession and moving date?
1. Cyber Homes
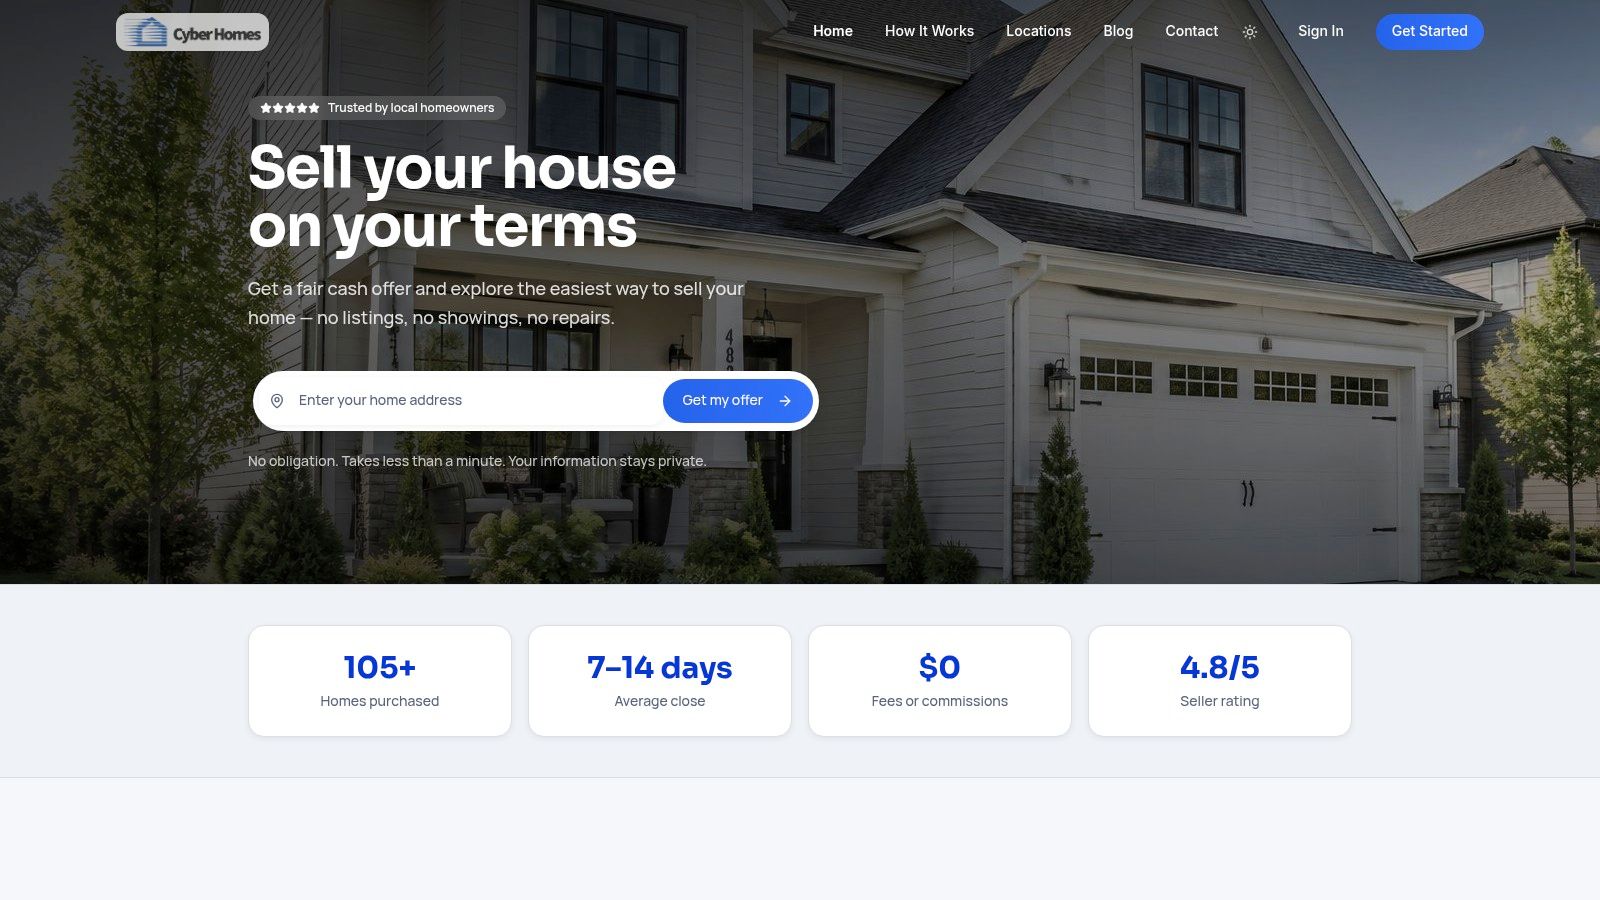
Cyber Homes is a family-owned cash home buyer that purchases properties as-is across major U.S. markets. The process targets owners who want a direct cash option without repairs, showings, agent commissions, or financing contingencies. Cyber Homes says sellers can usually receive an offer within 24 hours, and its locations page describes opening escrow by the next day.
For a divorce sale, assign one contact, but keep both spouses included. Request the same written offer, closing terms, title instructions, and possession expectations for each spouse, the title company, and the attorneys. Cyber Homes also says it covers standard closing costs and may advance up to $2,000 for moving expenses before closing. Put those terms in the purchase agreement, then have the title company confirm how proceeds will be distributed.
Where Cyber Homes fits best
This option may suit a home needing substantial work, a vacant or tenant-occupied property, or a couple that values a defined closing path over broad MLS exposure. Its average closing timeline is described as 7 to 14 days, though title clearance, lender payoff information, required signatures, and court orders can change the date.
The trade-off is price versus certainty. A direct investor offer accounts for repair, holding, and resale risk, so it may produce less than a successful MLS sale. Cyber Homes reports 105+ homes purchased and a 4.8/5 seller rating. Treat those figures as company-provided information, and still request proof of funds, confirm Boise-area eligibility, and compare the offer with an agent opinion or appraisal.
Pros
- Speed: Offers are commonly presented within 24 hours, with an advertised average close of 7 to 14 days.
- As-is convenience: Sellers can avoid repairs, staging, showings, and agent commissions.
- Transition support: Standard closing costs are covered, and moving assistance may be available.
- Personal communication: A family-owned team provides one consistent contact.
Cons
- Potentially lower proceeds: Convenience may reduce net proceeds compared with a well-executed MLS sale.
- Market eligibility: Confirm that the Boise-area property qualifies.
- Legal coordination: Both spouses must resolve authority, signatures, title, mortgage payoff, and distribution instructions before closing.
A written comparison should show the offer, estimated payoff, liens, closing costs, approved expenses, and each spouse's expected share. Have both spouses and their attorneys review the same documents before either person signs.
2. HomeVestors, We Buy Ugly Houses, Boise
HomeVestors gives Boise sellers access to a recognizable national brand through local franchise operators. The model centers on direct, as-is purchases, so owners may avoid repairs, staging, listing preparation, and repeated showings. A local representative usually inspects the property and explains the proposed process.
That approach can fit a divorce sale when the home has deferred maintenance, inherited contents, damage, or a difficult occupancy situation. It may also help if one spouse wants a familiar process while the other prioritizes a defined closing timeline. Local operators can discuss scheduling with the title company, but the buyer's availability does not override mortgage, title, attorney, or court requirements.
Check the local operator before signing
The national name does not establish the terms of a particular Boise transaction. The franchise operator controls the valuation method, responsiveness, contract language, and communication process. Ask who will sign the purchase agreement, whether the operator will close directly, and whether the contract permits an assignment or another investor's resale interest.
For spouses, the practical test is the written net. Request the offer, estimated deductions, closing costs, and proposed date in one document. Then compare that figure with an MLS net estimate or appraisal. Each spouse should review the same paperwork with counsel, especially if the offer is lower than the expected retail proceeds but reduces repair work, holding costs, or delay. For background on the structure, review how as-is home buyers work.
Pros
- Brand recognition: The national system may make the process easier to understand.
- As-is sale: Repairs, listing preparation, and showings may be avoided.
- Local appointment: A Boise-area franchisee can inspect the property and discuss timing.
- Defined process: The transaction follows a structured path from evaluation to closing.
Cons
- Franchise variation: Service quality and offer terms can differ by operator.
- Below-retail pricing: The offer may produce less than the eventual net from an MLS sale.
- Contract review needs: Confirm assignment rights, cancellation terms, and the actual closing party.
- Divorce coordination: Both spouses must address authority, signatures, title, payoff, and distribution instructions.
Website: HomeVestors Boise
3. EasySale
EasySale is a Boise-based, licensed and insured homebuyer serving the Treasure Valley since 2010. Its materials compare an investor sale with listing through an agent, which fits a divorce decision where the headline offer is only one part of the analysis. The relevant figure is each spouse's expected net after repairs, commissions, closing costs, mortgage payoff, holding costs, and timing.
EasySale promotes cash purchases without repairs, showings, or financing contingencies. It also reports purchasing 500+ homes from Idaho families. Treat that company-reported figure as background, not as proof of the property's current value. Request the offer, deductions, closing costs, closing date, and any conditions in writing before either spouse agrees to terms.
Where the offer may fit
A local direct buyer can help when neither spouse wants to manage repairs, staging, or repeated showings. It may also reduce disruption during a contentious separation, particularly when privacy and a predictable closing date matter more than testing the retail market.
Confirm that the exact Boise or Treasure Valley address falls within EasySale's active service area. Geographic eligibility does not establish that the offer is financially preferable. Investor pricing accounts for repairs, resale risk, and carrying costs, so a cash sale may provide greater certainty while producing less than an MLS transaction.
Each spouse should prepare the same comparison before discussing the split:
- estimated MLS sale price or appraisal value
- repair and preparation budget
- expected listing and closing costs
- mortgage payoff, liens, and other debts
- projected cash offer and closing timeline
- proposed distribution after approved obligations
An attorney can then coordinate the sale terms with any agreement or court order. A local buyer may make communication easier, but cannot resolve disputed ownership, required signatures, or the division of proceeds.
Pros
- Local experience: The company focuses on Boise and the Treasure Valley.
- Net-proceeds education: Its materials distinguish gross price from take-home proceeds.
- As-is process: Repairs, staging, and repeated access may be avoided.
- Direct communication: Local contact can simplify scheduling.
Cons
- Service-area limits: Confirm eligibility for the exact property.
- Investor discount: Pricing reflects risk, repairs, and resale costs.
- Shared approval still matters: Attorney and court requirements remain separate from the buyer's process.
4. Home Buyer Boise
Home Buyer Boise focuses on Boise and nearby Treasure Valley communities. Its materials describe no fees and no commissions, as-is purchases, flexible closing dates, and seller-cost explanations. For divorcing spouses, those details provide a useful starting point, but “no commission” does not automatically mean the highest net proceeds.
The company may suit owners who want a local contact and a direct explanation of the proposed price, covered costs, and closing schedule. Flexible timing can help if one spouse needs to relocate, remove belongings, or arrange temporary housing. It may also reduce disputes over repairs and property access.
Compare the offer with the settlement figures
Treat the fee explanation as an opening question, not a final accounting. Request a written estimate from the title company showing the mortgage payoff, liens, taxes, recording charges, agreed closing expenses, and each spouse's expected distribution. If the buyer describes the transaction as fee-free, confirm whether the quoted offer is the amount before payoff or whether costs remain outside that figure.
Each spouse should review the same documents and compare the cash proposal with an estimated MLS outcome. Include preparation expenses, expected marketing time, insurance, utilities, mortgage payments, and the value of a certain closing date. A local buyer can explain its process, but attorneys and court orders still control required signatures, ownership disputes, and the division of proceeds.
Pros
- Cost clarity: The company explains its no-fee and no-commission position.
- Local focus: Boise-area familiarity may support a more relevant property discussion.
- Flexible closing: The date may fit relocation needs and the legal schedule.
- As-is convenience: The property can be evaluated without a repair campaign.
Cons
- Limited geography: Confirm coverage for the precise Boise or Treasure Valley address.
- Lower ceiling: A direct offer may fall below a successful open-market sale.
- Documentation burden: Both spouses need matching written terms and payoff assumptions.
Website: Home Buyer Boise
5. Boise House Buyers
Boise House Buyers is a local team that advertises direct purchases across Idaho, including properties needing repairs, inherited homes, and time-sensitive moves. It promotes quick offers and closings through local title companies. A closing in about a week may be possible in some cases, but title work, lender review, and court requirements can change that schedule.
This option may suit a house with damaged flooring, an outdated kitchen, deferred exterior work, or personal property that would complicate showings. An as-is offer can also reduce disputes over repair budgets, contractor selection, and which spouse will manage the work.
Verify the buyer and compare the exit plan
Before signing, request the buyer's legal name, proof of funds, title company, inspection rights, proposed closing date, possession terms, and any assignment language. Ask whether Boise House Buyers will purchase the property directly or transfer the contract to another entity. Confirm service availability for the exact address rather than assuming the same process applies throughout Idaho.
For a divorce sale, keep both spouses on the same written record. Compare the offer with an estimated MLS result after repairs, commissions, holding costs, insurance, utilities, mortgage payments, and the value of a predictable closing date. Have the title company show the expected payoff and distribution, then let the attorneys confirm that the contract and closing instructions comply with court orders.
Pros
- Fast intake: Owners can request a direct quote online or by phone.
- Condition flexibility: Repair-heavy and inherited properties may be considered.
- Local knowledge: Boise-area familiarity can support a more relevant property review.
- Title coordination: A local title company can identify payoff and closing requirements.
Cons
- Timeline uncertainty: A quick closing depends on the property and paperwork.
- Coverage confirmation: Availability should be checked address by address.
- Investor pricing: Speed may reduce the equity available compared with an MLS sale.
Website: Boise House Buyers
6. Breeze Home Buyers
Breeze Home Buyers serves Boise, Meridian, Nampa, Caldwell, and nearby South Idaho communities. Sellers can request an as-is offer, avoid showings and commissions, choose a preferred closing date, and receive updates by phone or text.
For divorcing spouses, simple communication helps only when it supports a shared record. Keep the offer, contract, inspection notes, title updates, payoff figures, and distribution instructions in one document. Confirm ownership and proceeds decisions in writing, and provide the record to the relevant attorneys.
When a simple process helps
Breeze may suit spouses who agree on the basic sale objective but want fewer moving parts during a fast transaction. Its Treasure Valley coverage also makes it relevant for homes outside Boise, including Meridian, Nampa, and Caldwell. Confirm service for the exact address and identify whether Breeze or another investor will appear as the purchaser.
The trade-off is verification. Personal service may make communication easier, but it does not replace proof that the buyer can close. Request proof of funds, the buyer's legal name, the title company, inspection rights, and the proposed closing date before signing. Do not rely on a verbal promise that the purchase is cash or that the date is guaranteed.
For the divorce file, compare expected net proceeds with an MLS estimate after commissions, repairs, holding costs, utilities, mortgage payments, and the value of certainty. Ask the title company to show the payoff and proposed distribution. Attorneys should confirm that the contract and closing instructions match any court orders.
Pros
- Treasure Valley coverage: The service includes major Boise-metro cities.
- Flexible scheduling: The closing date can be discussed around family and legal needs.
- Simple communication: Phone, web, and text updates can reduce missed messages.
- As-is purchase: Repairs and showings may be removed from the spouses' workload.
Cons
- Proof-of-funds review: Confirm the buyer's ability to close.
- Operator scale: A smaller team may have fewer backup resources if problems arise.
- Lower retail potential: Investor terms usually favor certainty over maximum price.
Website: Breeze Home Buyers
7. Idaho House Buyer, Treasure Valley Property Solutions
Idaho House Buyer, also known as Treasure Valley Property Solutions focuses on Boise and the surrounding Treasure Valley. It promotes all-cash, no-obligation offers and advertises closings in as little as 7 days. Its stated options include a direct purchase and possible investor resale routes.
That flexibility may help with a property that is difficult to price or needs substantial work. It also creates a question divorcing spouses should settle before signing: who will buy the home and fund the closing? Assignment or resale plans are not automatically a problem, but the contract should identify the buyer, disclose assignment rights, and state who remains responsible if another investor does not perform.
Review the contract before accepting
Check the buyer's legal name, earnest-money terms, inspection period, cancellation rights, proof of funds, and proposed closing date. Ask the title company how an assignment would affect documents and proceeds, and confirm what each spouse must sign. Attorneys should review any provision that changes the buyer or distribution instructions, especially when a court order controls the sale.
Compare the offer's expected net proceeds with an agent comparative market analysis, an independent appraisal, and the costs of an MLS listing. Include repairs, cleaning, staging, commissions, holding costs, mortgage payments, utilities, and removal of personal property. A quick closing has value only when both spouses understand the net amount and the contract provides a dependable exit.
Use the company's website and its Northwest Indiana pre-listing preparation resource for preparation ideas, but verify all property-specific terms directly with the buyer and title company.
Pros
- Local focus: The firm works with Boise and Treasure Valley properties.
- Disposition flexibility: A direct purchase or investor resale path may be available.
- Fast-close option: The company advertises closing in as little as seven days.
- As-is possibility: Fewer repairs and showings may reduce the spouses' workload.
Cons
- Buyer verification: Confirm who will provide funds and sign at closing.
- Investor margin: Pricing reflects resale risk and transaction costs.
- Divorce coordination: Attorneys should align the contract, title work, and proceeds plan with any court orders.
Website: Treasure Valley Property Solutions
8. Choosing Between an MLS Sale and a Cash Buyer
A Boise couple facing divorce may value different outcomes. One spouse may want the highest possible proceeds, while the other needs a predictable closing date and fewer repairs. Compare net proceeds plus certainty, not a cash offer with the MLS list price alone. Realtor.com describes Boise as balanced, with about 1.3K homes for sale and a $625K median listing price in August 2026. Redfin reported homes selling in a median of 12 days during the three months ending August 2026. These measures provide context, not a promise for one property. Review Realtor.com's Boise market page and Redfin's Boise housing data, then obtain property-specific opinions.
Side-by-side worksheet
Each spouse should complete the same worksheet independently before discussing an offer:
- Estimated sale price: Record an agent's MLS opinion, an appraisal result, and each written cash offer.
- Property costs: Include repairs, cleaning, staging, inspections, and removal of personal property.
- Transaction costs: List commissions, closing costs, taxes, title charges, and concessions where applicable.
- Carrying costs: Estimate mortgage payments, utilities, insurance, maintenance, and vacancy exposure during the expected sale period.
- Debt and deductions: Enter the mortgage payoff, home-equity loans, liens, and approved expenses.
- Expected net: Calculate the amount available for distribution, not the headline price.
- Certainty: Check financing conditions, inspection rights, closing timing, cancellation terms, and proof of funds.
A lower cash offer may fit when the home needs extensive work, relocation is urgent, or carrying costs are burdensome. Use written estimates, and confirm how the cash-sale process works through this guide to how companies buy homes for cash. Have attorneys confirm that the chosen contract and proceeds plan comply with any divorce agreement or court order.
9. Documenting Value, Equity, and Each Spouse's Share
A cash offer is one valuation input, not the value of the home. Before either spouse accepts an offer or proposes a buyout, collect several defensible views. An agent's comparative market analysis reflects a possible MLS strategy. An independent appraisal provides a formal opinion. Written cash offers show what specific buyers will pay under their repair, timing, and resale assumptions.
Record the same valuation date for both spouses. Attorneys should confirm whether the controlling date comes from a separation agreement, court order, filing, or another legal event. Keep every report, offer, and assumption in one shared file.
Equity worksheet
Use this calculation:
Agreed sale price minus mortgage payoff, liens, taxes, closing costs, and approved sale expenses equals distributable proceeds.
Document these items:
- Valuation date: Apply one date to each estimate.
- Debt balances: Attach current mortgage and home-equity payoff statements.
- Property deductions: List liens, taxes, repairs, title charges, and moving expenses.
- Ownership record: Review the deed, vesting, separate contributions, reimbursements, and marital-property rules.
- Proposed split: State the percentage or dollar allocation under consideration.
- Approval status: Identify whether both spouses, attorneys, lenders, and the court have approved it.
A lower cash offer may still produce a better result if repairs, delay, or carrying costs reduce the expected net from an MLS sale. Compare net proceeds and closing certainty, not headline price. The same recordkeeping used to get fair ACV from insurers helps preserve the assumptions and documents supporting the calculation.
A valuation does not decide legal ownership. Title, contributions, reimbursement claims, marital-property rules, and court orders may require legal interpretation. Have attorneys confirm the proposed split and sale contract before either spouse signs.
10. Clearing Mortgage, Title, and Court Requirements
A cash buyer may be ready to close while the property still cannot legally transfer. Divorce can create conflicts among the deed, mortgage, separation agreement, temporary orders, and final judgment. Open the title process early, particularly if one spouse has moved or communication is limited.
Transaction-readiness process
- Request a current payoff: Ask the mortgage servicer for a written payoff valid through the expected closing date.
- Identify other debt: Check for home-equity loans, tax balances, judgments, utility liens, and recorded claims.
- Review the deed: Confirm vesting, legal names, ownership interests, and required signatures.
- Ask the title company: Confirm required marital, lender, identity, notarization, and court documents.
- Check the court file: Have the attorneys identify orders controlling the sale, possession, signatures, or proceeds.
- Coordinate with the lender: A sale usually pays the mortgage at closing, but that payoff does not release a borrower from liability beforehand. A buyout may require lender approval or refinancing.
Practical rule: Keep one shared written record instead of relying on separate conversations with the buyer.
Send material updates to both spouses and their attorneys, and record decisions in the shared file. Give the buyer one consistent set of instructions about price, possession, repairs, and distributions. The title company confirms transfer requirements, the lender verifies debt payoff, attorneys interpret legal rights, and the spouses approve the business terms.
Requirements depend on the deed, loan, liens, and court orders. Obtain title and legal guidance if either spouse disputes signing authority, ownership, or the proposed distribution. Before signing, have the attorneys confirm that the contract, payoff instructions, and proceeds plan match the applicable orders.
11. A 30-Day Path From Agreement to Closing
A 30-day plan creates tasks and deadlines, not a guaranteed closing date. Title defects, lender questions, disputed signatures, attorney review, or short-sale approval can extend the schedule. Let the title company confirm the required sequence.
Days 1 through 30
- Days 1–3: Each spouse states the objective, such as speed, maximum net proceeds, or a clean move. Gather the deed, mortgage statements, court documents, insurance details, leases, and repair records.
- Days 4–7: Obtain an agent opinion, an appraisal when appropriate, and written cash offers. Compare expected net proceeds, timing, certainty, and conditions in one shared worksheet.
- Days 8–14: Choose the MLS or cash-buyer path, verify the buyer's proof of funds, and address title or attorney approvals.
- Days 15–21: Sign the reviewed contract, then complete buyer, lender, and title requirements.
- Days 22–30: Review the settlement statement, confirm payoff and distribution calculations, sign closing documents, and coordinate possession and moving.
On closing day, confirm keys, utilities, personal property, forwarding details, and wire-fraud precautions. Both spouses need written confirmation of each distribution's amount and destination. Verify wire instructions through a trusted phone number obtained independently, never from an email alone.
Use this guide to selling a house as-is when organizing disclosures and practical preparation. “As-is” does not remove known-defect disclosure duties or title requirements. Keep the contract, valuation worksheet, payoff figures, and proceeds plan consistent with attorney guidance and any court order.
Boise Cash Home Buyers: 11-Point Comparison
| Option | 🔄 Complexity | 💡 Resources required | ⚡ Speed / Efficiency | 📊 Expected outcomes ⭐ | Ideal use cases |
|---|---|---|---|---|---|
| Cyber Homes | Low, streamlined local process, one point of contact | Minimal paperwork; local buyer, standard closing docs; moving advance available | ⚡ Very fast, offers ~24 hrs; close in 7–14 days | 📊 Certainty & convenience; ⭐⭐⭐⭐ (price below MLS) | Sellers needing speed/certainty, avoid repairs/showings (foreclosure/probate/relocation) |
| HomeVestors (We Buy Ugly Houses) – Boise | Low–Medium, national playbook with local franchise variation | In‑person visit, standard transaction docs | ⚡ Fast, quick in‑person offers and local closings | 📊 Predictable off‑market sale; ⭐⭐⭐ (price typically below MLS) | Sellers wanting brand recognition and a repeatable process |
| EasySale | Low, experienced local buyer with transparent comparisons | Documents + fee/net proceeds comparisons; local market data | ⚡ Fast, cash offers, no showings | 📊 Clear net‑proceeds comparisons; ⭐⭐⭐⭐ (strong local tenure) | Treasure Valley sellers wanting transparent estimates and local expertise |
| Home Buyer Boise | Low, upfront fees and process explained | Standard seller docs; flexible closing coordination | ⚡ Fast, as‑is purchases with flexible timing | 📊 Upfront cost clarity; ⭐⭐⭐ | Sellers wanting clear costs, timelines, and local specialization |
| Boise House Buyers | Low, simple intake via web or phone | Verify service area, proof of funds, title coordination | ⚡ Fast, offers and closings often quick (≈1 week situational) | 📊 Quick resolution for problem properties; ⭐⭐⭐ | Inherited homes, repair‑heavy properties, time‑sensitive moves |
| Breeze Home Buyers | Low, streamlined, mobile‑friendly communications | Online form, phone/text updates, confirm funds/title | ⚡ Flexible & responsive, seller‑chosen closings | 📊 Convenience and communication focus; ⭐⭐⭐ | Sellers who prioritize simple communication and flexible closing dates |
| Idaho House Buyer (Treasure Valley Property Solutions) | Low–Medium, local investor with multiple disposition paths | Proof of cash, title checks, may reassign to investors; has BBB listing | ⚡ Fast, advertises closings in as little as 7 days | 📊 Flexible disposition options; ⭐⭐⭐ | Complex dispositions or sellers needing very quick closings |
| Choosing Between an MLS Sale and a Cash Buyer (planning) | Medium, requires gathering and comparing estimates | Multiple valuations, repair estimates, carrying & closing cost calculations | ⚡ N/A (planning), MLS typically slower than cash | 📊 Net‑proceeds focused decision tool; ⭐⭐⭐⭐ | Couples weighing top‑market price vs speed/certainty; pre‑sale planning |
| Documenting Value, Equity, and Each Spouse's Share | Medium, evidence collection and calculations | Agent CMA, independent appraisal, written offers, attorney input | ⚡ N/A, accuracy‑focused, may take time | 📊 Defensible equity allocation; ⭐⭐⭐⭐ | Divorcing couples or buyout negotiations needing documented valuations |
| Clearing Mortgage, Title, and Court Requirements | High, legal/title/lender checks and approvals | Payoff statements, lien searches, title company, attorneys, possible court docs | ⚡ May slow process, depends on lenders/courts | 📊 Transaction readiness & fewer closing blockers; ⭐⭐⭐ | Transactions with liens, complex vesting, lender or court involvement |
| A 30‑Day Path From Agreement to Closing | Low–Medium, structured, milestone driven | Documents, valuations, title & lender coordination, settlement review | ⚡ Designed for ~30‑day close (adaptable) | 📊 Milestone clarity and reduced last‑minute surprises; ⭐⭐⭐ | Sellers who want a concise, timed roadmap to close quickly |
Choose Certainty With a Documented Exit Plan
The best choice isn't automatically the highest advertised number or the fastest promise. It's the route that matches the spouses' agreed goals, verified net proceeds, legal obligations, property condition, and required timing.
A cash buyer can be valuable when repairs, showings, financing contingencies, foreclosure risk, probate, relocation, tenant issues, or conflict make an MLS sale difficult. Boise's market still moves quickly in many cases. Zillow reported a typical Boise home value of $503,852, up 1.8% year over year, with homes going pending in about 9 days and 34.9% of sales closing over list price in August 2026. Those indicators show why a seller shouldn't assume urgency alone justifies accepting the first investor offer. See Zillow's Boise home-value data for the cited market signals.
The local cash environment also remains relevant. Intermountain MLS data showed 21.9% of Boise sales were cash purchases in 2021, compared with 16.7% in 2016, while a separate Boise-Treasure Valley analysis reported roughly 40% cash purchases around the same period. More recent reporting found investors owned 32.1% of single-family homes in Boise County, with 1,007 of 1,445 investor-owned properties held outright without financing. These figures help explain why cash models remain active, but they don't establish what your home is worth or what either spouse should accept. The market data appears in this Boise housing investment analysis.
Compare written offers from more than one buyer where possible. Confirm the service area, proof of funds, title company, closing date, inspection rights, assignment provisions, cancellation terms, and every cost deducted from proceeds. Then have the mortgage payoff and lien figures verified before anyone calculates a division.
The contract or closing instructions should identify both spouses' responsibilities, required signatures, possession arrangements, and distributions. If the transaction affects ownership, support, debt, or a court order, obtain attorney guidance before signing. A buyer's urgency doesn't override a spouse's legal rights or a lender's requirements.
Use this action list:
- Align goals: Agree on urgency, price expectations, possession, and communication rules.
- Order documents: Obtain valuations, mortgage payoffs, lien information, and title records.
- Compare paths: Evaluate MLS, investor sale, buyout, and short-sale options using net proceeds.
- Document approvals: Put decisions, responsibilities, signatures, and distributions in writing.
- Review settlement: Verify every payoff, deduction, and final distribution before signing.
Cyber Homes offers Boise-area sellers a no-obligation cash offer, an as-is process without repairs or commissions, and a closing date coordinated with the household's needs. For divorcing spouses who need a clear, documented exit plan, visit Cyber Homes to submit the property details and discuss the next step with the team.
Edited by
James Vasquez
Real Estate Investor & Land Specialist with 10+ years experience in residential flipping, vacant land investing, land wholesaling, and subdivision deals.
Disclaimer: The information provided is for educational purposes and does not constitute financial or legal advice. Always consult with licensed professionals before making investment decisions.